The self-storage industry rarely questions growth. Expansion—whether through ground-up development, add-on acquisitions, or organic lease-up—carries an almost automatic assumption of value creation. More units, the logic goes, means more revenue, lower operating costs per unit, and a stronger exit multiple down the road.
But in today's market, that assumption is increasingly fragile. For many operators in the Southwest, the choice between doubling down on expansion and executing a disciplined disposition isn't really about ambition—it's about whether you're willing to accept lower returns in the name of scale.
The Math Stops Working in Saturated Markets
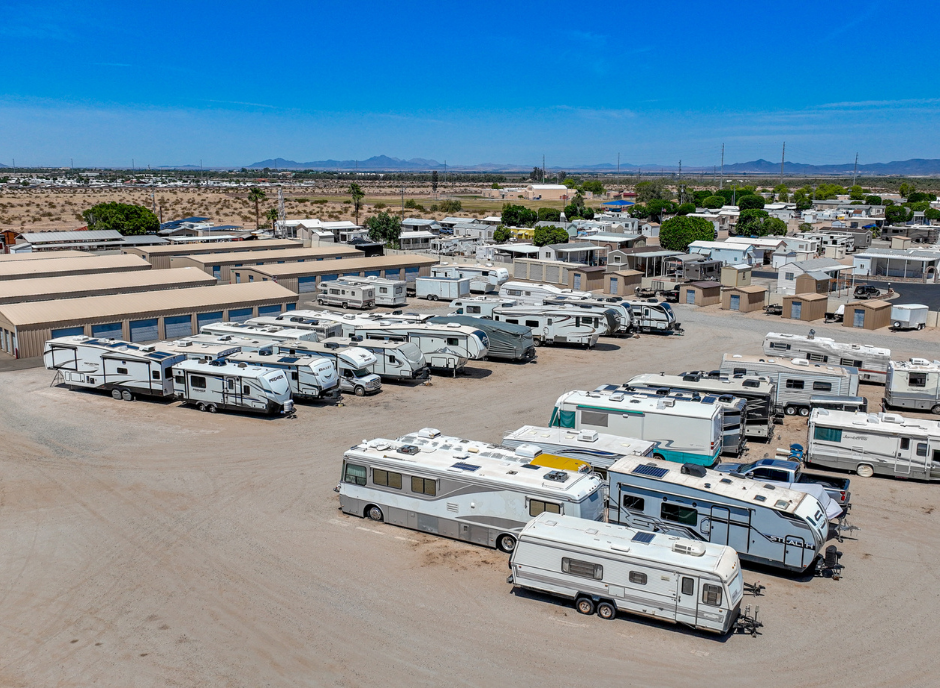
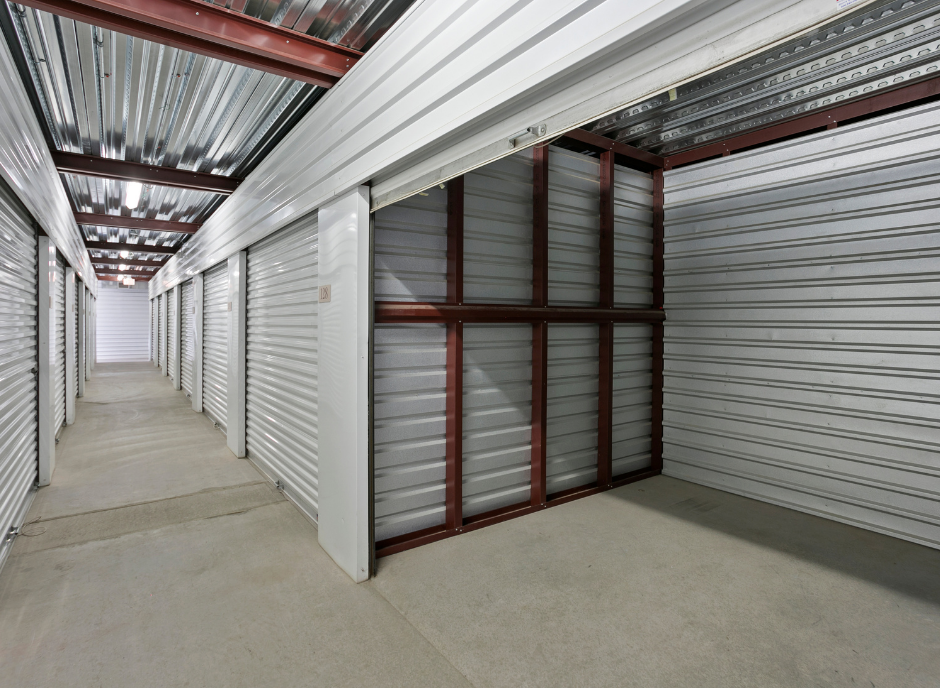
Consider a self-storage operator in Phoenix with a stabilized, fully-leased 85,000-square-foot facility yielding a 6.5% cap rate. That property represents clean, predictable cash flow with a clear exit story. An adjacent 40,000-square-foot add-on acquisition or ground-up project becomes available at a 5.8% cap rate—common in today's market.
The conventional pitch: combine portfolios, reduce overhead per unit, extract synergies, push the blended cap rate higher over time.
The reality: you're anchoring your portfolio to a lower-yielding asset that will take 18-24 months to stabilize, require active management during the lease-up phase, and likely plateau at the same 5.8% cap rate or lower. Your portfolio-level return hasn't improved—it's been diluted by the weight of a lower-yielding anchor.
In a rising-rate environment with compressed cap rates across the board, this is a compounding problem. Every expansion done at 100-150 basis points below your stabilized yield erodes your overall portfolio return, even if the pro-forma math looks neutral after three years.
Operator Overconfidence vs. Market Cycle Reality
Expansion decisions often rest on operator confidence: "We've executed lease-up before. We know how to market aggressively. We'll achieve above-market occupancy velocity."
This is where the Southwest supply cycle becomes dangerous. Phoenix and Las Vegas have both added meaningful new supply over the past 24 months. That new competitive inventory—combined with less-than-peak pricing power for new facilities—means lease-up velocity has slowed compared to 2021-2022 benchmarks. The operator who successfully stabilized a facility in 2019 may find a very different market in 2024.
Expansion decisions made in 2022 looked brilliant. Expansion decisions made in 2024, in markets already adjusting to higher supply, carry more risk than their pro-forma underwriting suggests.
The Disposition Case Gets Stronger
Now consider the alternative: taking that same stabilized 85,000-square-foot facility, selling it at a 6.5% cap rate while buyer demand remains competitive, and deploying that capital—or more likely, stepping back and taking a partial or full exit.
For an owner who's held the asset 7-10 years, that exit removes execution risk, locks in a known return, and frees capital that doesn't have to be redeployed into a lower-yielding expansion.
More importantly, a disciplined exit during a market window—before supply dynamics push cap rates wider and before occupancy velocity slows further—is a sophisticated form of portfolio management. It's the opposite of indiscriminate growth. It's choosing quality of return over quantity of units.
When Bigger Actually Means Weaker
Portfolio growth creates operational complexity that operators often underestimate:
A portfolio of three stabilized, higher-yielding facilities often generates more predictable returns than a portfolio of five with one or two in lease-up. Yet the five-facility operator will typically command a lower exit multiple, not higher, because of execution and occupancy risk.
The Seller's Advantage in 2026
For self-storage operators evaluating their portfolio over the next 12-24 months, the math of disposition remains compelling:
The operators who expanded aggressively in 2022-2023 are now managing lease-up headwinds. The operators who stabilized assets pre-2023 are looking at facilities that have held occupancy and pricing power through a tighter cycle. Exiting a stabilized, proven asset in 2026—rather than chasing further growth—is the smarter play.
Expansion isn't inherently bad. But in a market where new supply is still being absorbed and where cap rate compression has reversed, the operator who recognizes that selling at current yields might be smarter than buying into a slower-leasing environment—is likely to outperform.
Sometimes the best deal is the one you don't do.
If you want to talk through your property, Connect with the Gorden Group or request a property valuation