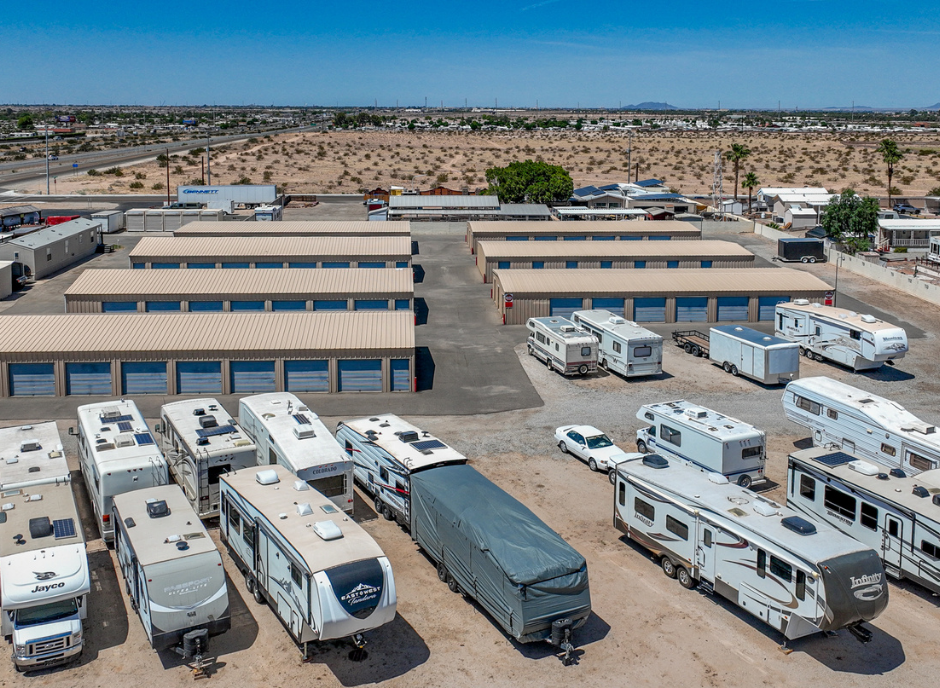
The self-storage landscape of 2026 looks dramatically different from the REIT-dominated consolidation narrative of five years ago. While institutional portfolios still command significant market share, independent operators—mom-and-pop owners running single to mid-size portfolios—are holding their ground in ways that surprise many market observers. Understanding who's actually winning requires looking beyond market cap and into how each operator segment is adapting to today's occupancy velocity challenges, cap rate compression, and increasingly selective buyer pools.
The Current Playing Field
The 2026 storage market has fundamentally shifted from a supply-constrained tailwind to a supply-normalized environment. Occupancy rates across the Southwest—particularly in Phoenix, Las Vegas, and Salt Lake City—have settled into the 85–90% range for stabilized assets, down from the 93%+ peaks of 2023–2024. This matters enormously because it changes the operational playbook for every participant.
REITs enter this environment with structural advantages: access to cheap capital (though credit spreads have normalized), scale in marketing spend, and the ability to absorb non-performing periods across a diversified portfolio. Public storage companies like Public Storage, CubeSmart, and Extra Space Storage can weather occupancy dips in specific markets because they're modeling enterprise-level performance across hundreds of facilities.
But here's where the story gets interesting: that same scale, which was a competitive moat in a rising tide, has become a constraint in a normalized market.
Where Mom-and-Pop Operators Are Winning
Independent operators—especially those with deep local relationships and 10–50 unit portfolios—are outperforming market expectations in three critical ways:
1. Pricing Flexibility and Dynamic Micro-Targeting
REITs manage pricing through sophisticated revenue management systems (Silo, StorFront, and Apptis are industry standards), which optimize occupancy and rate across entire geographies. This approach works beautifully in supply-constrained markets but becomes a liability when supply normalizes.
Mom-and-pop operators, conversely, are nimble. They can adjust move-in specials, month-to-month lease incentives, and rate positioning within 48 hours—not the quarterly adjustments typical of corporate systems. In 2026, when occupancy velocity has slowed and tenant acquisition costs are climbing, this agility translates into faster fills and better average daily rates on the margin.
Several independent operators we've worked with in Phoenix have reported stabilizing occupancy 6-8 weeks faster than institutional comparables by leveraging hyper-local promotional partnerships and relationship-driven tenant acquisition. REITs, by contrast, are bound by corporate branding guidelines and centralized marketing playbooks.
2. Operational Cost Discipline Without Corporate Overhead
The REIT model requires layers: regional operations managers, corporate compliance, investor relations, and centralized finance teams. These overhead structures are essential for public companies but expensive at smaller scales.
Independent operators don't have that burden. A 20-unit portfolio generating $150K–$200K in annual NOI can be managed by one property manager and an owner with a 15% operating expense ratio. Try achieving that across a REIT portfolio—the corporate structure alone would eat 8–12 points of NOI.
In today's cap rate environment (mid-5% range for stabilized Southwest assets), every basis point of expense savings directly flows to the bottom line. That makes mom-and-pop portfolios naturally more profitable on a yield basis, even if absolute NOI dollars are smaller.
3. Seller-Friendly Transaction Structures
This is where the competitive advantage cuts deepest for independent operators buying portfolios from exiting owners.
REITs move capital efficiently but operate on spreadsheet logic. They're buying portfolios that fit acquisition thresholds, NOI targets, and geographic clustering. If your property is slightly outside their thesis, or if your rent roster includes quirky lease terms they want to re-underwrite, the REIT pass is likely.
Independent operators buying up smaller portfolios—especially in secondary markets within the Southwest—don't have those institutional constraints. They'll accept longer lease-up periods, less-than-perfect occupancy, and non-traditional tenant mixes if the underlying real estate and NOI trajectory make sense. For sellers, this means real optionality in a more competitive exit environment.
Where REITs Still Control the Narrative
Don't mistake this analysis for a proclamation that REITs are in decline. They're not. They control significant advantages:
Capital Access: REIT balance sheets can deploy $50M+ into a portfolio acquisition in a single quarter. Mom-and-pop operators simply cannot compete on speed or scale.
Institutional Buyer Appeal: If you're a seller with a $40M+ portfolio, REITs remain your primary exit avenue. Their ability to close quickly, manage complexity, and underwrite at scale is unmatched.
Market Presence: REITs have brand recognition, corporate tenant relationships, and the ability to cross-sell ancillary services (climate-controlled units, vehicle storage, logistics) that diversify revenue. Independents can't replicate that economically.
Portfolio Optionality: REITs can hold underperforming assets in high-appreciation markets, absorbing temporary occupancy troughs because future appreciation is baked into the thesis. Independents need current cash flow to survive.
The Market Bifurcation Accelerates
What we're seeing in 2026 is a sharpening split:
What This Means for Owners Timing an Exit
If you're evaluating disposition timing, the competitive dynamics between independent operators and REITs are worth understanding—not because one is inherently "better," but because it affects your actual buyer pool and exit valuation.
A property that would have commanded a 4.75% exit cap rate in a REIT-competitive scenario might exit to an independent buyer at 5.25%—a half-turn difference. Whether that matters depends on your exit objectives. If you're selling because you want to redeploy capital into a 1031 exchange, REIT buyers offer speed and certainty. If you're timing around a retirement or need operational flexibility in your exit process, independent operators and regional buyers offer more accommodating transaction structures.
REITs will continue aggregating properties that fit their thesis. But the 2026 storage market has proven that mom-and-pop operators, properly capitalized and strategically positioned, are holding market share because they're solving problems that spreadsheet-driven portfolios can't.
The narrative of inevitable consolidation undersells the competitive advantages of local knowledge, operational agility, and relationship-driven deal-making. In a normalized supply environment, those advantages matter more than they did five years ago.
Ready to evaluate your exit options? At Gorden Group, we work with sellers across the spectrum—from single-property operators to large portfolio holders. We understand both the REIT buyer playbook and the independent operator landscape. If you're timing a disposition or exploring strategic options, let's talk about which buyer profile actually fits your goals.
If you want to talk through your property, Connect with the Gorden Group or request a property valuation